
Air travel across the globe is outgrowing the airports that serve it. Rather than building more airports, governments are expanding and extending concessions (government-granted rights to run an entire airport) with incumbent operators. This trend strengthens the quasi-monopoly position and profit growth of this week’s Long Idea.
The company runs 52 airports across six countries, with the majority located in Latin America. Despite long-standing competitive advantages and attractive growth prospects, the stock price implies that the company’s profits will never grow beyond their current level.
The best opportunities arise when strong profits and growth prospects collide with low expectations.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- monopoly or near-monopoly position in each of its key markets,
- long-dated concessions with U.S. dollar-denominated or inflation-indexed tariffs,
- peer-leading NOPAT margin and ROIC,
- strong free cash flow and new dividend, and
- cheap stock valuation that implies no NOPAT growth from current levels.
Latin America’s Growing Appetite for Air Travel
Air travel in Latin America is on the rise.
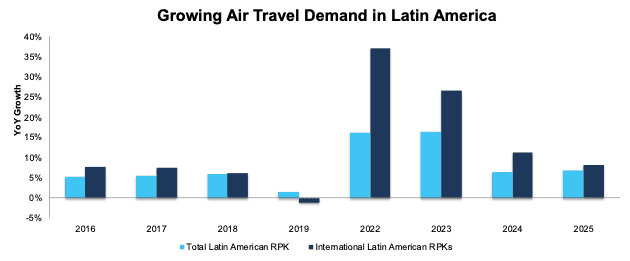
According to the International Air Transport Association (IATA), Latin American international revenue passenger kilometers (RPKs), a measure of passenger demand, grew by an average of 5.1% per year between 2016 and 2019, while total Latin American RPKs grew by an average of 4.5% per year over the same time.
Fast forward to more recent trends, and we see dramatic acceleration in RPKs. From 2022-2025, Latin American international RPKs and total Latin American RPKs grew by an average of 20.8% and 11.4%. See Figure 1.
Figure 1: Year-Over-Year Latin American RPK Growth: 2016-2025 – Excluding COVID (2020-2021)
Sources: IATA
*We exclude COVID’s impact in 2020 and 2021 on air travel for visualization purposes. For reference, total Latin American RPK fell 57% and 23% YoY in 2020 and 2021, respectively while Latin American International RPK fell 76% and 40% YoY over the same time.
As societies grow richer, the appetite for air travel grows too.
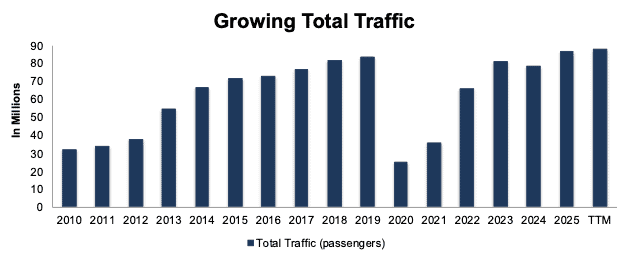
In the decade prior to the pandemic, this company’s total traffic, measured in millions of passengers, grew 11% compounded annually. In 2025, total traffic beat its pre-pandemic high. See Figure 3.
Rising GDP and standards of living across the globe provide a strong tailwind for future growth in total passengers.
Figure 3: Growing Total Traffic: 2010 – TTM
Sources: New Constructs, LLC and company filings
Durable, Profitable Growth
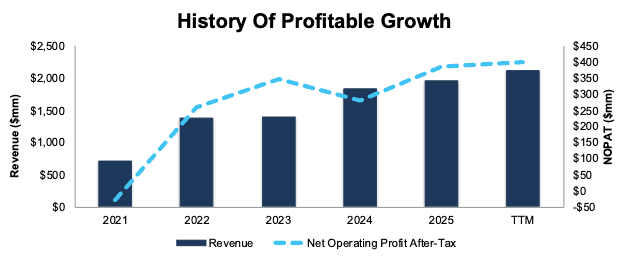
This company has leveraged its quasi-monopolistic market positions and the tailwinds in air travel to grow revenue by 27% compounded annually since 2021. Net operating profit after-tax (NOPAT) grew from -$27 million in 2021 to $399 million in the trailing-twelve-months (TTM).
The company improved its NOPAT margin from -4% in 2021 to 19% in the TTM, while its invested capital (IC) turns, a measure of balance sheet efficiency, improved from 0.2 to 0.6 over the same time.
Rising NOPAT margins and IC turns drive the company’s return on invested capital (ROIC) from -1% in 2021 to 11% in the TTM.
Figure 4: Revenue and NOPAT: 2021 – TTM
Sources: New Constructs, LLC and company filings
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.