
Today, with a new CEO at the helm, this company generates near record profits.
However, the current stock price is much too low and implies profits will permanently decline by 20%.
The disconnect between company fundamentals and pessimistic expectations for future profits creates Attractive risk/reward.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- position as a top 3 grocery retailer in the U.S.,
- strong growth in private label and ecommerce operations,
- strong cash flows that support shareholder return, and
- cheap valuation.
Private-Label is a Key Profit Driver
Consumers are buying private label products at record levels. According to Circana, over the 10-month period ended November 1, 2026, private label unit sales increased 0.1% while national brand sales declined 0.9%. Private label unit share increased to a record 23.7% over the same time. These private-label products generate higher margins for retailers.
This company has invested in its private label brands to profit from this consumer shift. In the 12 months ended January 31, 2026, the company’s private label products generated over $39 billion in sales.
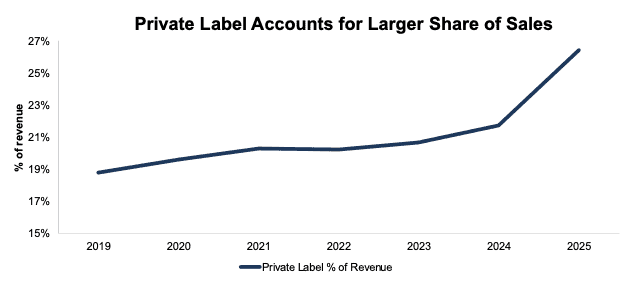
Private label sales have grown from 19% of revenue in 2019 to 26% of revenue in 2025. See Figure 2.
Better yet, the company has grown private label sales 8% compounded annually over the past five years, while total food-at-home (FAH) nominal expenditures in the U.S. grew 5% compounded annually over the same time.
Figure 2: Private Label Sales as a Percent of Revenue: 2019 – 2025
Sources: New Constructs, LLC and company filings
Decades of Consistent Profit Growth
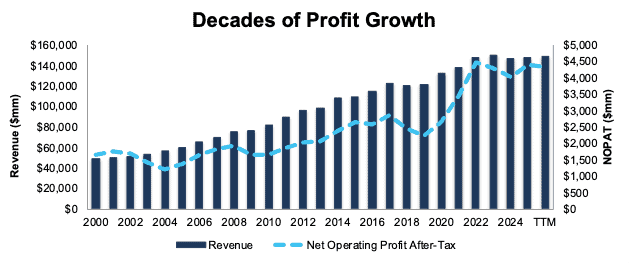
Despite YoY fluctuations, this company has grown profits across 25+ years. Since 2000, the company has grown both revenue and NOPAT by 4% compounded annually. See Figure 5.
Since 2020, the company improved its NOPAT margin from 2.0% to 2.9% over the TTM, while invested capital turns improved from 2.8 to 2.9 over the same time. Rising margins and IC turns drive return on invested capital (ROIC) from 6% in 2020 to 8% over the TTM.
Figure 5: Revenue and NOPAT: 2000 – TTM
Sources: New Constructs, LLC and company filings
Significant Cash Flow Generation
The company has consistently turned rising sales and profits into strong free cash flow (FCF), which supports its shareholder capital return plans.
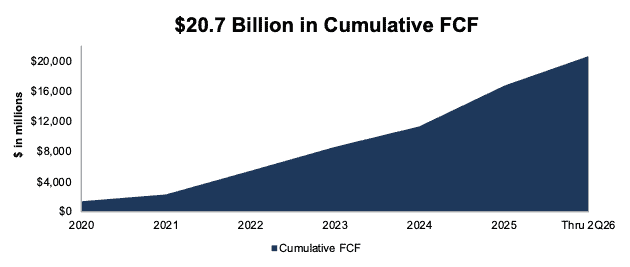
The company generated a cumulative $20.7 billion (31% of enterprise value) in FCF from 2020 through 2Q26. In just the TTM period, the company generated $7.3 billion in FCF.
Perhaps most impressive, the company has generated positive FCF in 23 calendar years since 2000.
Figure 6: Cumulative Free Cash Flow: 2020 – 2Q26
Sources: New Constructs, LLC and company filings
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.