
Health does not wait for the economy, interest rates, or the stock market. As the U.S. population grows older and behavioral health demands expand, more Americans will require care at a time when the supply of healthcare services remains constrained.
These trends create an opportunity for providers with the capacity, scale, and expertise to profit from growing demand. Yet, investors are valuing specific healthcare companies as if this opportunity doesn’t exist.
We first made this stock a Long Idea in October 2025. Since then, the market has failed to realize the strength of the business. We’re here to remind investors, this stock offers Very Attractive risk/reward.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- an aging population driving medical services demand,
- worsening mental health driving behavioral services demand,
- rising admissions and revenue per admissions,
- a strong track-record of revenue and profit growth,
- strong free cash flow and shareholder returns, and
- a cheap stock valuation.
U.S. Population is Getting Older by the Day
From 2020 to 2025, the U.S. population age 65 and older grew 16.2%, while the population under age 18 declined 2.4%.
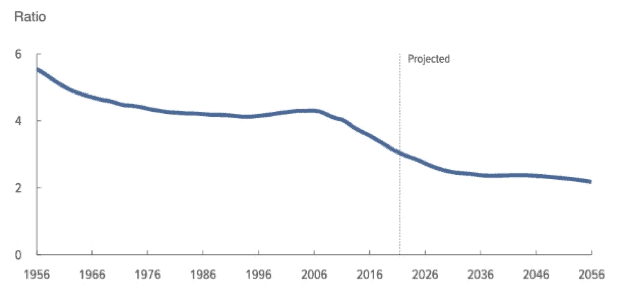
This trend is not likely to change anytime soon. The Congressional Budget Office projects the ratio of people ages 25-64 to people ages 65+ will decline from 2.7 to 1 in 2026 to 2.2 to 1 by 2056. Figure 1 illustrates how this ratio has steadily declined since the 1950s.
Additionally, Brookings estimates the population of 80+ year olds will increase from 14.7 million in 2025 to 29.4 million in 2045. Additionally, they estimate 70+ year olds as a percent of the population will rise from 12.9% in 2025 to 17.2% in 2045 while those under the age of 15 will fall from 17.2% to 15.5% of the population over the same time.
Figure 1: The Ratio of 25-64 Year Olds to 65+ Year Olds: 1956 Through 2056
Sources: Congressional Budget Office
Healthcare Spend Rises with Age
It’s simple but remains true: an aging population drives more healthcare spending.
The latest Centers for Medicare & Medicaid services (CMS.gov) data shows that the per capita spending of a person aged 85 or older is 8.5x higher than the spending of a child aged 18 or under. For those aged 65-84, healthcare spending is 4.9x higher than those aged <18. See Figure 2 in the full report.
Strong Revenue and Profit Growth
This company has a proven track record of growing revenue and profits alongside rising industry demand.
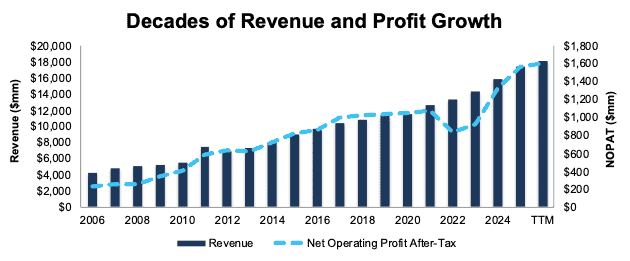
The company has grown revenue and net operating profit after-tax (NOPAT) by 8% and 11% compounded annually, respectively, since 2006.
Additionally, the company’s Core Earnings grew 12% compounded annually over the same time.
The company improved its NOPAT margin from 5% in 2006 to 9% in the TTM even as invested capital turns fell from 1.5 to 1.3 over the same time. Rising NOPAT margins offset invested capital turns and drive the company’s ROIC from 8% in 2006 to 12% in the TTM.
More recently, the company has grown revenue and NOPAT 8% and 9% compounded annually since 2021, respectively.
Figure 6: Revenue and NOPAT Since 2006
Sources: New Constructs, LLC and company filings
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.