
This Long Idea is up 146% since we first featured it.
Today, the company generates record profits with multiple long-term growth tailwinds, yet the current valuation of stock implies large catastrophic profit decline.
The disconnect between strong fundamentals and overly pessimistic expectations for future profits creates a Very Attractive opportunity.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- proven ability to capitalize on growing demand,
- consistent profit growth across decades,
- strong cash flows and shareholder return, and
- cheap valuation.
Consistent Demand for Its Products
This company benefits from consistent demand for auto and home insurance. According to Mordor Intelligence, from 2026-2031:
- the U.S. motor insurance market is projected to grow 9% compounded annually.
- the U.S. homeowners insurance market is projected to grow 5% compounded annually.
These growth rates provide consistent opportunity for this company, as U.S. citizens are required to have insurance for owning, renting, or leasing housing and vehicles.
Profits Reaching Record Highs
We’ve previously noted that the company’s profits quickly rebounded after a steep downturn in 2022 and 2023. The quick rebound was the result of price hikes and underwriting restrictions that drove the company’s combined ratio down and profits up.
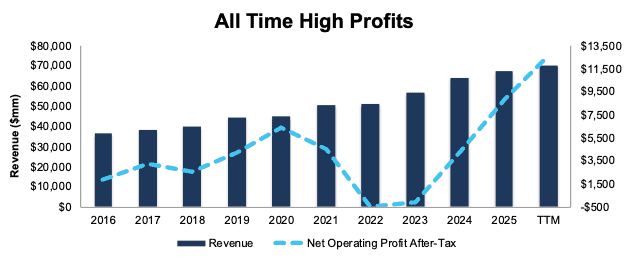
Figure 2 shows that rebound has continued. The company’s net operating profit after-tax (NOPAT) reached $12.7 billion over the trailing-twelve-months (TTM), which is the company’s highest NOPAT over any 12 month period since 1998.
The company improved its NOPAT margin from -0.9% in 2022 to 18.1% over the TTM, while invested capital turns improved from 1.8 to 2.0 over the same time. Rising margins and IC turns drive return on invested capital (ROIC) from -2% in 2022 to 36% over the TTM.
Beyond the last few years, the company has grown revenue 7% compounded annually over the past 10 years and 3% compounded annually over the past 20 years. The company has grown NOPAT 18% and 10% compounded annually over the same timeframes.
Figure 2: Revenue and NOPAT: 2016 – TTM Ended 2Q26
Sources: New Constructs, LLC and company filings
Significant Cash Flow Generation
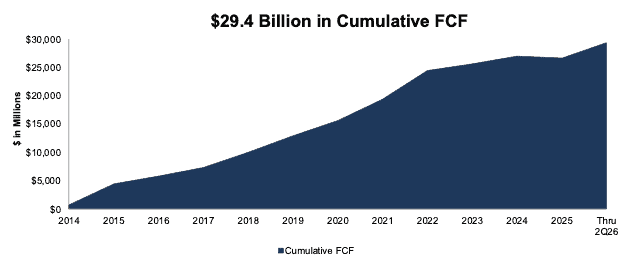
This company has consistently generated large cash flows across decades and generated a cumulative $29.4 billion (49% of enterprise value) in FCF from 2014 through 2Q26. See Figure 5 from the full report.
Figure 5: Cumulative Free Cash Flow Since 2014
Sources: New Constructs, LLC and company filings
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.