
This Long Idea is up 152% since we first featured it.
The company has leveraged rising energy demand and operational improvement to grow its bottom-line to record highs.
Going forward, the company is positioned to profit from long-term demand tailwinds for years to come, yet the current valuation of the stock implies profits will permanently fall.
The disconnect between strong profit growth and overly pessimistic expectations for future profits creates Attractive Risk/Reward.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- long-term energy demand tailwinds,
- asset efficiency and decades of reserves,
- improving fundamentals,
- high shareholder return backed by strong cash flows,
- quality balance sheet, and
- undervalued stock price
Oil and Gas Are Still Energy Kings
The fact remains that energy demand is expected to rise through at least 2050, while oil and gas remain the largest sources of energy. According to OPEC’s 2026 World Oil Outlook, oil and gas are expected to make up 54% of the global energy mix in 2050.
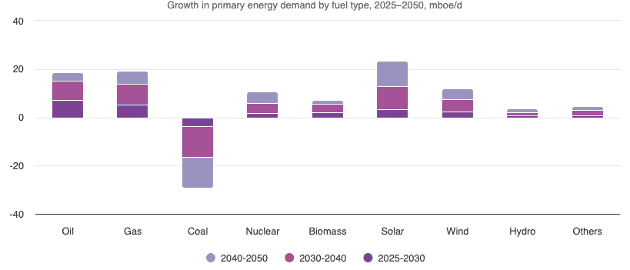
OPEC forecasts global primary energy demand will increase from 312 barrels of oil equivalent a day (mboe/d) in 2025 to 383 mboe/d in 2050, or a 23% rise. OPEC estimates renewables (51 mboe/d), gas (19 mboe/d), and oil (19 mboe/d) will see the largest increase in demand from 2025 through 2050. See Figure 1.
This leading oil and gas provider is positioned to benefit from this long-term trend for years to come.
Figure 1: Growth in Global Energy Demand by Fuel Type: 2025 – 2050
Sources: OPEC
Improving Fundamentals
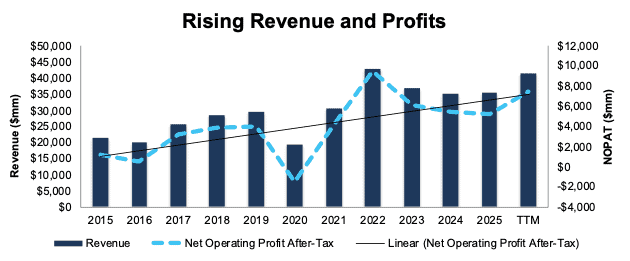
The company has leveraged rising energy demand and its operational improvement to grow both the top and bottom-line. The company has grown revenue and NOPAT by 7% and 14% compounded annually since 2021.
The company improved its NOPAT margin from 14% in 2021 to 18% in the TTM while invested capital turns rose from 0.4 to 0.5 over the same time. Rising NOPAT margins and invested capital turns drive the company’s ROIC from 6% in 2021 to 10% in the TTM ended 2Q26.
Additionally, the company’s Core Earnings, a superior and cleaner earnings measure, grew 17% compounded annually from $3.3 billion in 2021 to $6.7 billion in the TTM.
Figure 4: Revenue and NOPAT: 2015 – TTM
Sources: New Constructs, LLC and company filings
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.