
This week’s Long Idea is one of the largest healthcare services companies in the U.S., with operations spanning acute-care hospitals, ambulatory surgery centers, and related healthcare services.
The company is pivoting to focus on expanding one of the largest outpatient surgery platforms in the country and actively reducing reliance on traditional acute-care hospitals. As more healthcare moves to lower-cost outpatient settings, the company stands to profit from this faster-growing, higher-margin business.
The market is pricing the stock as if this shift has no value, and that the company cannot mitigate the ongoing reimbursement risks. In fact, the stock is priced as if the company’s profits will permanently fall 50%.
We think that expectation is far too pessimistic and creates Very Attractive Risk/Reward.
Below, we provide an excerpt from our latest Long Idea report. Get the full report a la carte here.
This stock presents quality Risk/Reward based on the company’s:
- leading position in the growing U.S. ambulatory surgery market,
- continued expansion of its higher-margin outpatient care business,
- strong FCF generation that supports billions in share repurchases,
- top-tier profitability amongst peers, and
- cheap stock price that implies profits will permanently decline from current levels.
Technology and Policy Are Moving the Market to Lower-Cost Outpatient Services
Along with regulatory policy changes, advances in medical technology, surgical techniques, and anesthesia are driving a growing number of surgical procedures to outpatient settings.
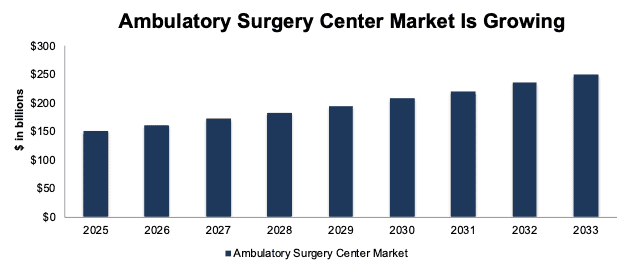
Ambulatory surgery centers (ASCs) are a key driver and beneficiary of this shift. These facilities specialize in surgeries and other procedures that do not require overnight stays and, as a result, cost less. The ASC market is projected to grow 7% compounded annually through 2031. See Figure 1.
Figure 1: Projected Growth in ASC Market (2025-2033)
Source: New Constructs, LLC and Grand View Research
A Doubling of Profits
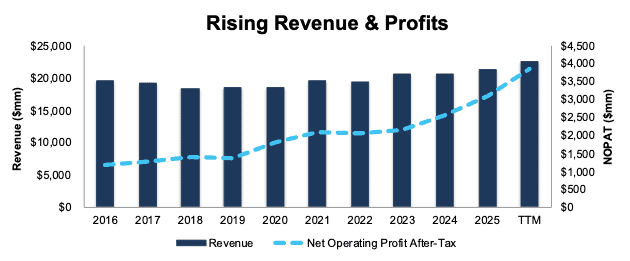
This company has proven it can generate substantial profit growth without relying on rapid revenue growth. Since 2016, the company has grown revenue and net operating profit after-tax (NOPAT) 2% and 13% compounded annually, respectively.
The company improved its NOPAT margin from 6% in 2016 to 17% over the trailing-twelve-months (TTM), while its invested capital (IC) turns, a measure of balance sheet efficiency, remained at 0.8 over the same time. Rising margins and consistent IC turns drive return on invested capital (ROIC) from 5% in 2016 to 13% over the TTM.
Perhaps most impressive, economic earnings, the true cash flows of the business, remained positive in every year, and increased from $611 million in 2016 to $2.0 billion over the TTM.
As the company continues growing its higher-margin ambulatory care while improving its hospital operations, further margin expansion could drive additional profit growth even without rapid top-line growth.
Figure 4: Revenue and NOPAT: 2016 – TTM
Sources: New Constructs, LLC and company filings
Potential for ~7% or Higher Buyback Yield
The company returns capital to shareholders through share repurchases rather than dividends. As profitability and free cash flow have improved, the company has also become more aggressive with its buybacks.
From 2022 through 2Q26, the company repurchased approximately $3.9 billion worth of shares. The pace of repurchases has accelerated substantially this year, with the company repurchasing $1.4 billion shares in the first six months of the year alone.
In June 2026, the company’s board authorized an additional $2 billion for share repurchases. As of June 30, 2026, the company had $2.1 billion remaining under its repurchase authorizations.
Should the company repurchase shares at its 2025 pace, it would repurchase an additional $1.4 billion shares over the next 12 months, which equals 6.9% of the current market cap.
…there’s much more in the full report. You can buy the report a la carte here.
Or, become a Professional or Institutional member – they get all Long Idea reports.
Interested in starting your membership to get access to more of our research? Get more details here.