REITs and Financial Stocks Are “Most Dangerous” for December
The December version of our Most Attractive Stocks and Most Dangerous Stocks reports are now available for purchase. Note that Barron's recently recognized our Most Attractive Stocks portfolio as #1 over the prior 12 months amongst the best of the Wall Street research firms.
 David Trainer, Founder & CEO
Fundamental Research for ETFs & Mutual Funds: Look Out Morningstar
Ever wondered what it would be like to evaluate funds and ETFs with the same rigor that you can evaluate individual stocks - that is exactly what we deliver in the our Mutual Fund Rating and ETF Reports. Samples provided
David Trainer, Founder & CEO
The Leak on WikiLeaks – Regulators Knew About Risks That Led to Financial Fallout
While I cannot predict what WikiLeaks will leak about some major banks, I have a hunch that one of the revelations might be from a special New Constructs report provided to the Senate Banking Committee’s Subcommittee on Securities, Insurance, and Investment.
David Trainer, Founder & CEO
Stock Pick of the Week: JDA Software Group Inc (JDAS) – Very Dangerous Rating
Red Flags:
1. Misleading earnings: JDAS reported a $14.6mm increase in GAAP earnings while our model shows economic earnings declined by $12.9mm (a difference of $27.5mm or 155% of reported net income).
2. Very dangerous valuation: stock price of $27 implies JDAS must grow its NOPAT at over 20% compounded annually for 10 years. A 10-year growth appreciation period with a 20%+ compounding growth rate sets expectations for future cash flow performance quite high.
3. Free Cash Flow was -$203mm or -15% of the company’s enterprise value last year.
4. Asset write-offs of $21mm or 3% of net assets – this means that management has written off at least $0.03 of assets for every $1 on the current balance sheet. Writing off assets is the opposite of creating shareholder value as it reflects management’s inability to derive any profits for the investments it makes with shareholder funds.
5. Off-balance sheet debt of $40mm or 6% of net assets.
6. Outstanding stock option liability of $13mm or 1% of current market value.
David Trainer, Founder & CEO
Buy The Travelers Co (TRV) – Very Attractive Rating
HIDDEN GEMS:
1. About $29 million in non-operating expenses (after-tax) cause reported earnings to be understated.
2. Our dis¬counted cash flow analy¬sis shows that TRV’s cur¬rent val¬u¬a¬tion (stock price of $55.49) implies that the company’s profits will decline by 30% and never grow again.
3. The company grew its economic earn¬ings by $827mm during its last fiscal year.
David Trainer, Founder & CEO
Bernanke’s Masterstroke Puts the Ball In the Fiscal Policy Court
Contrary to nearly every headline you read about monetary policy these days, I believe it is quite possible the Fed Chairmen Ben Bernanke is performing quite well and much better than any of his recent predecessors. In fact, I think he is directing monetary policy with unprecedented precision and skill.
David Trainer, Founder & CEO
Western Digital Corp (WDC) – free report for Ask Matt, Very Attractive Rating
HIDDEN GEM: Our detailed valuation model shows that WDC grew its “economic” profits by 226% while accounting profits grew 194% during its last fiscal year. Economic profits rose by $769mm while accounting profits rose by $912mm.
David Trainer, Founder & CEO
Initiation of Coverage of ETFs
Today we initiated coverage of ETFs for all major sectors and Indices. Free samples of the initiation reports are here. These reports deliver strategic insights into entire sectors and markets.
David Trainer, Founder & CEO
How Artificially Low Interest Rates Harm Economies in the Long Term
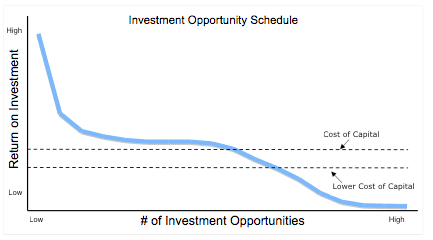
Maintaining artificially low interest rates or excessive money supply does permanent damage to economies in the medium and long-term because it delays creative destruction, the process of replacing low-return investments with higher-return investments. To help illustrate this point, I present the “Investment Opportunity Schedule” in Exhibit 1
David Trainer, Founder & CEO
Stock Pick of the Week: Akamai Technologies Inc (AKAM) – Very Dangerous Rating
RED FLAGS:
1. Misleading Earnings: AKAM reported a $1mm increase in GAAP earnings while our model shows economic earnings declined by $10mm (a difference of $11mm or 7% of reported net income).
2. Very Dangerous Valuation: Stock price of $47 implies AKAM must grow its NOPAT at over 20% com¬pounded annu¬ally for 15 years. A 15-year growth appreciation period with a 20%+ compounding growth rate sets expectations for future cash flow performance quite high.
3. Asset write-offs of $2,000mm or 102% of Net Assets – this means that management has written off at least $1 of assets for every $1 on the current balance sheet. Writing off assets is the opposite of creating shareholder value as it reflects management’s inability to derive any profits for the investments it makes with shareholder funds.
4. Off-balance sheet debt of $128mm or 7% of Net Assets.
5. Outstanding Stock Option Liability of $212mm or 3% of current market value.
David Trainer, Founder & CEO
S&P 500 Is Fully Valued
The Risk/Reward of the entire S&P 500 gets our Neutral Rating. Our recently published Index Benchmark report on the S&P 500 offers unique insights into the underlying profitability and valuation of all the companies comprised by this index. It also offers benchmarks for (1) investors considering buying ETFs or Index Funds based on the S&P 500 and for (2) comparing individual stocks to the S&P 500.
David Trainer, Founder & CEO
Small Cap Stocks Are Dangerous
The Risk/Reward of the entire Russell 2000 gets our Dangerous Rating. Our recently published Index Benchmark report on the Russell 2000 offers unique insights into the underlying profitability and valuation of all the companies comprised by this index. It also offers benchmarks for (1) investors considering buying ETFs or Index Funds based on the Russell 2000 and for (2) comparing individual stocks to the Russell 2000.
David Trainer, Founder & CEO
Stock Pick of the Week: Buy Colgate-Palmolive Co (CL) – Very Attractive Rating
HIDDEN GEMS:
1. About $250 million in non-operating expenses (after-tax) cause reported earnings to be understated during the last fiscal year.
2. Our discounted cash flow analysis shows that CL’s current valuation (stock price of $77.52) implies that the company’s profits will decline by 7% and never grow again.
3. The company grew its economic earnings by $229mm (14% increase) during its last fiscal year.
David Trainer, Founder & CEO
Stock Pick of the Week: Short Rackspace Hosting Inc (RAX) – Ignore the Takeover Hype
RED FLAGS:
1. Misleading Earnings: RAX reported a $30mm increase in GAAP earnings while our model shows economic earnings declined by $13mm (a difference of $43mm or 7% of revenue).
2. Very Dangerous Valuation: Stock price of $25.636 implies RAX must grow its NOPAT at 25% compounded annually for 17 years. A 17-year Growth Appreciation Period with a 25% compounding growth rate is quite a high standard to beat, as per my post on How To Make Money Picking Stocks.
3. Outstanding Stock Option Liability of $205mm or 6.5% of current market value
David Trainer, Founder & CEO
MSFT up 8.3% – former Stock Pick of Week on Oct 28
MSFT released better than expected earnings and is up 8.3% since it was named the Stock Pick of the Week on October 28, 2010. Overt the same time period, the S&P 500 is up only 3.6%.
David Trainer, Founder & CEO
Red Flag Report: Alternative Fuel Mixture Credit (AFMC) Windfall
The second report in our Red Flag series focuses on a little-known earnings Windfall in the Paper and Products Industry. This report is another example of the deep analysis New Constructs performs on all 3000+ companies under coverage. Our expertise is in navigating poor and confusing disclosure in the Financial Footnotes to find the truth about corporate profitability and valuation.
David Trainer, Founder & CEO
Wall Street’s Secret Plans To Continue Raiding the Capital Markets
In another excellent expose "Wall Street Proprietary Trading Under Cover", Michael Lewis exposes Wall Street's plan to exploit loopholes in the laws and regs to continue proprietary trading, the activity that was the primary downfall of Bear Stearns and Lehman Brothers.
David Trainer, Founder & CEO
Stock Pick of the Week: Buy Bristol Myers Squibb Co (BMY) – Very Attractive Rating
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that BMY’s current valuation (stock price of $27.16) implies that the company’s profits will decline by 35% and never grow again.
2. The company grew its economic earnings by $307.5mm (12% increase) during its last fiscal year.
3. The company has $9,507mm in Excess Cash, which we remove from our Invested Capital calculation. $9,507mm million is more than 20% of BMY’s market cap.
David Trainer, Founder & CEO
Apple Inc (AAPL) — Attractive Rating — for Ask Matt Readers
HIDDEN GEM: AAPL's economic earnings rose more than its accounting earnings during the last fiscal year. Economic earnings rose by $3,576 while accounting earnings rose by $2,401. And the company has $31,849mm in Excess Cash, a reflection of the strong profitability of the business.
David Trainer, Founder & CEO