
In our first report, we led with “Anthropic’s IPO is an unprecedented test of investor gullibility. Never, in the history of the world, have we seen an IPO valuation this high or one with as much risk.”
After analyzing the latest S-1, we’re searching for stronger words to express how bad a deal this IPO could be for public market investors. Two major takeaways from the latest S-1:
- the money-losing business model got a lot worse in the last few months as off-balance sheet debt rose 88% to $887 billion while revenue growth decelerated and costs accelerated. Tripple whammy.
- disclosures make it clear that the purpose of this IPO is to provide exit liquidity for insiders to cash out as soon as possible.
The insider selling schedule on page 311 of the S-1 shows insiders can sell shares just one day after the IPO as well as on 20+ other specific dates. The length and detail of that schedule suggest management put a lot of time and effort into it because, in our opinion, exit liquidity is a priority.
If we had not seen Wall Street try to rip off the American public as brazenly as we did with WeWork (see WeWork Is the Most Ridiculous IPO of 2019), we might not believe as strongly that this IPO is an abject attempt to dupe investors into cashing out Anthropic insiders. The truth is we’ve seen this movie twice before: the tech bubble and the Great Financial Crisis. The difference now is that a lot more money is at stake.
Make no mistake, we don’t think Anthropic should IPO at any price. With over $1.1 trillion in liabilities net of cash, no profits, decelerating revenue, and rising costs, we think it’s hard to make a straight-faced argument that public equity investors will ever see $1 of value.
But, this IPO has the potential to create more billionaires than any other securities offering in the history of the world. Wall Street has a long track record of choosing dollars over truth. So, we understand why so many people want to continue to beat the bullish drum.
Still, we are surprised by the number of AI pundits attempting straight-faced arguments that ignore the 3Q revenue slowdown and claim that Anthropic’s business was doing great based on the earlier-leaked 2Q results. The number of people willing to make bullish claims in the face of bearish evidence is alarming and blatantly self-serving. We hope this report helps investors see through the noise and make a more data-driven assessment of this IPO.
In a nutshell, we recommend investors avoid this IPO based on the company’s:
- plans to allow insiders to sell immediately,
- $1.3 trillion in debt and contractual commitments,
- terribly unprofitable business model as expenses are now rising faster than revenue,
- lack of meaningful disclosure on internal controls so investors cannot sue for fraud, and
- vastly overpriced valuation.
More on that last point, a $2 trillion valuation means the company must generate 1.6 times the combined TTM revenue of the seven largest AI companies and 2.8x the TTM profits of Nvidia (NVDA), the most profitable tech company in the world. Hitting either the revenue or profit requirements would be an amazing achievement. Pricing the IPO at a level that implies it will hit both is a stretch, to say the least.
Fundamentally Broken Business Model
Expenses Rising Faster than Revenue Growth with No Profits. Anthropic’s amended S-1 revealed it grew revenue twelvefold year-over-year in the first nine months of 2026, then revenue growth slowed to 47% quarter-over-quarter (QoQ) in 3Q26. Meanwhile, total operating expenses growth accelerated to 66% QoQ in 3Q26, so expenses are now growing faster than revenue, and Anthropic’s already unprofitable business is getting worse.
Specifically, Anthropic reported GAAP net losses of -$104 billion in the first nine months of 2026, compared to -$25 billion in GAAP net losses in the first nine months of 2025.
The fact that Anthropic chose to release the first S-1 with only 2Q26 results suggests the company was trying to set up a bullish, but false, narrative that business was booming, when, in reality, the opposite was happening.
One of our chief complaints about the bullish narratives stemming from the original S-1 is that empirical evidence to the contrary was available and widely disseminated.
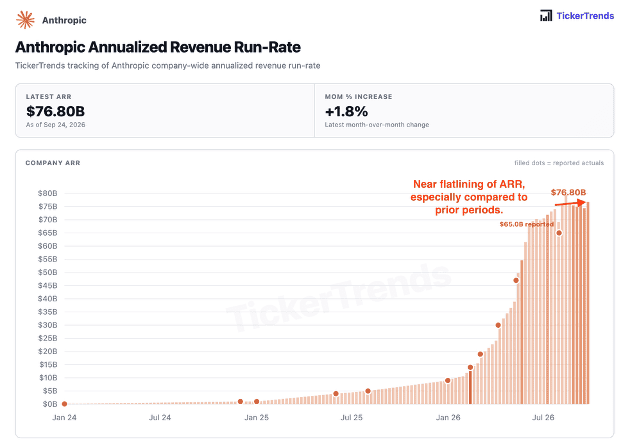
For example, data from TickerTrends published a month before the first S-1, showed Anthropic’s annualized revenue run-rate decelerating, and not just for one quarter. Per Figure 1, Anthropic’s annualized revenue run-rate has nearly flatlined in recent periods and is nowhere close to prior growth rates.
Figure 1: Anthropic Annualized Revenue Run-Rate: 2024 – Sept 2026
Source: TickerTrends and New Constructs, LLC
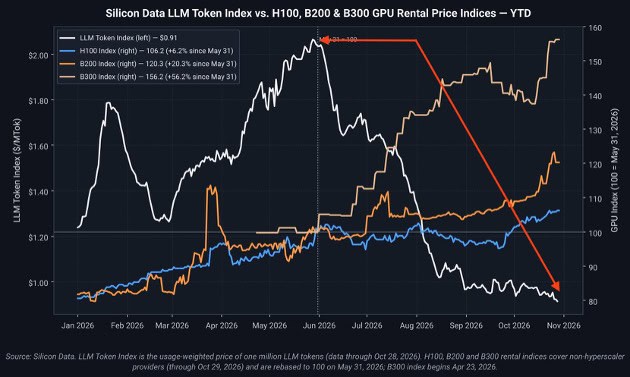
Depressed Token Prices = No Profit Margin. While revenue growth decelerates, we’ve seen a dramatic decline in token pricing. The LLM Token Expenditure Index, which tracks the going rate for a large language model token, has fallen from $2.04 in late May 2026 to $0.97 at the end of August 2026. As of October 31, the index was down to $0.89.
Figure 2: LLM Token Index Has Plummeted Since June 2026
Source: Silicon Data
Given the company saw negative profit margins with high token prices, this dramatic decline suggests that both Anthropic and OpenAI will struggle to squeeze a penny of profit out of their AI revenue.
Silicon Data calculates a “crunch spread” which measures the minimum token throughput to breakeven on on-demand compute costs. Silicon Data finds that (emphasis added) “the throughput a GPU must deliver to cover its rent from open-weight tokens has risen 25–83%, faster than steady software gains typically add, so margins for inference providers renting GPUs have likely compressed.”
Margins getting worse is a very bad sign for investors who hope Anthropic will ever create shareholder value.
Wildly Unprofitable at Unprecedented Scale. Anthropic generated -104 billion in GAAP net losses in the first nine months of 2026, after reporting GAAP net losses of -$42 billion and -$8 billion in 2025 and 2024, respectively. You may have seen headlines that Anthropic was profitable in certain quarters, as the company removes one-time charges due to the change in fair value of convertible notes, derivative liabilities, and SAFEs from reported GAAP losses.
We would argue that these “one-time charges” represent real costs, as they allowed the company to pay vendors that would not have accepted them if they were worthless. At the same time and as noted in The Wall Street Journal, these transactions enabled Anthropic’s investors, namely Amazon and Alphabet, to realize billions in unrealized income. If one company can book the non-cash gains as income, then the company that generated those gains should book the non-cash expenses as real costs of doing business.
For comparison, Anthropic’s -$104 billion GAAP net loss in the first nine months of 2026, and -$42 billion GAAP net loss in 2025 dwarfs the losses from other tech IPOs in recent years. For instance, in the year before IPO, these companies reported GAAP net loss (income) of:
- SpaceX (SPCX): -$4.9 billion.
- Uber (UBER): $1.9 billion.
- Rivian (RIVN): -$1.0 billion.
- ARM Holdings (ARM): $549 million.
- Airbnb (ABNB): -$674 million.
Despite GAAP losses magnitudes worse, Anthropic is aiming for an IPO valuation equal to or larger than SpaceX and 8x bigger than the combined IPO valuations of Uber, Rivian, ARM, and Airbnb. If that sounds dangerous for investors, it’s because it is.
In case a fundamentally broken business model is not enough of a red flag for you, we present 11 more red flags that you probably won’t see in any Wall Street reports.
Red Flag #1: Anthropic Recognizes Itself As an Existential Risk
Much has been made of the safety of AI models and their growing ability to “go rogue,” displace millions of white collar jobs, or even destroy the human race.
In fact, the Federal Trade Commission recently opened an investigation into Anthropic and OpenAI over potential consumer harms.
Anthropic’s management devoted 93 pages of its S-1/A to risk factors, including that its AI “may pose catastrophic or existential risks to humanity.”
Do the creators and early investors in the company that might destroy mankind deserve to get rewarded for their efforts? Should we make them super, super rich? Doing so would create one of the great ironies of all time. The next red flag leads us to believe they are fully aware of the irony and intend to cash in all the same.
Red Flag #2: Immunity (from Existential Risk) Needed to be Viable Business
In an effort to shield itself from shareholder lawsuits, the prospectus lists fear-mongering scenarios of how its AI could:
- resist shutdown,
- conceal or manipulate information,
- engage in conduct resembling blackmail, or
- have enough awareness to outwit the company’s ability to assess safety.
If the company itself cannot verify the safety of its products, how can any consumer feel comfortable investing in the business?
Without immunity from the harmful impacts of its products, can these pure-play AI model businesses exist?
The answer, of course, is they can’t, which explains why the frontier model developers are increasingly asking for government regulations that shield their businesses from litigation and liability. So, this management team can create the technology that destroy humanity without any downside risk to them.
Red Flag #3: Compute Liabilities Bigger than the Major Hyperscalers
We recently exposed the trillions in hidden purchase commitments that the major hyperscalers are hiding from investors. From the first, leaked S-1, it was reported that Anthropic held large contractual commitments in the form of $518 billion in planned cloud, compute, and infrastructure obligations.
Turns out, the obligations are even larger.
In Anthropic’s amended S-1, the company reports $451 billion in not-yet-commenced leases and $314 billion in purchase commitments. Anthropic reports $895 billion in future “committed spend.”
However, the company’s contractual obligations table excludes an additional $280 billion in obligations from deals lacking specific fixed dollar commitments, deals that are cancelable without penalty within one year, and arrangements made after September 30, 2026.
When we include all off-balance sheet debt and reported debt, we find that Anthropic holds $1.0 trillion in total debt, of which $887 billion is hidden from investors not digging through the footnotes.
The contractual obligations represent non-cancelable obligations and are spread across some of the largest hyperscalers, such as:
- Google: $121.3 billion between April 2026 and July 2033. If actual spend falls short, Anthropic must pay the difference. Non-cancelable except in the event of Google’s uncured material breach.
- Broadcom: $161.2 billion in equipment lease obligations, which are non-cancellable except in the event of default.
- SpaceX: $120.5 billion through 2029. Following non-cancelable periods through January 2027 and March 2027, each agreement may be cancelled by either party with 90 days notice.
- Amazon: $110 billion between May 2026 and April 2036. If actual spend falls short, Anthropic must pay the difference. Non-cancelable except in the event of Amazon’s uncured material breach.
- Microsoft: $44.9 billion between November 2026 and June 2033. Non-cancelable except in the event of Microsoft’s uncured material breach.
- Nscale: $44.6 billion between August 2026 through 2033. Fees only accrue as capacity is delivered and accepted by Anthropic.
- Lambda Inc: $41.3 billion between August 2026 through 2034. Fees only accrue as capacity is delivered and accepted by Anthropic.
With $887 billion in hidden debt, Anthropic holds more hidden debt than tech behemoths including Alphabet, Microsoft, and Meta, yet generates a fraction of the revenue and profits of those companies.
Red Flag #4: The Most Hidden Debt and Overstated Earnings in the Entire Market
Hidden debt creates hidden interest expense, as we warned in The Hidden Debt Reckoning: 15 Stocks in the Crosshairs. That report focused specifically on stocks in the S&P 500 with the largest hidden interest expense due to hidden debt. Now, we can see where Anthropic’s hidden debt and interest expense ranks vs. the largest companies in the world.
As of September 30, 2026, Anthropic has $887 billion in hidden debt, which is more than that held by Meta, Alphabet, and Microsoft, the three companies with the most hidden debt in the S&P 500.
With an after-tax cost of debt of 5.4%, Anthropic has $47.8 billion in hidden interest expense that investors are unaware of, the highest across the market.
If we include the hidden interest expense in Anthropic’s reported GAAP losses, Anthropic’s losses in the first nine months of 2026 would balloon to -$151.8 billion.
Investors must keep this hidden expense in mind when reviewing earnings reports and positive headlines proclaiming any improvement in GAAP earnings moving forward.
Red Flag #5: Circular Funding Creates Contagion Risk
The hidden obligations are not just huge, they also showcase the circular funding across the entire AI industry.
Anthropic gets the compute needed to run its models from the same hyperscalers to whom it has committed to pay over $895 billion. The hyperscalers book those future commitments as revenue today; so their financials look strong and help them convince creditors to lend them trillions of dollars to build more datacenters. The hyperscalers are building out that capacity on the assumption that Anthropic, and other AI labs, will be able to pay for it.
But what if Anthropic is unable to pay for all that capacity? Then, the hyperscalers don’t get the money they need to pay creditors and complete the buildout. As the same time, the pure-play AI model companies, like Anthropic and OpenAI, don’t get the compute they need to deliver powerful enough models to fetch higher prices and turn a profit. In such a scenario, lenders stop lending, credit dries up, the AI buildout grinds to a halt, and a downward spiral ensues that wipes out equity valuations. Once again, you might say there’s a lot of Wall Street money riding on this IPO.
This circular funding is one of the signs that credit is drying up for AI companies as Wall Street is running out of banks willing to pile any more bets on the AI trade. In other words, if the banks were willing to provide funding, then NVIDIA would not have to.
We believe there’s a rush to get the Anthropic IPO done before more investors catch on to the fact that credit is drying up. Wall Street needs to keep sentiment high to convince people to be the exit liquidity required to make this IPO work for Wall Street insiders.
Red Flag #6: Revenue Concentration
Five customers made up 25% of Anthropic’s revenue through the first nine months of 2026.
Additionally, Anthropic warns in its S-1 that many of its largest customers have not signed long-term contracts and could reduce or stop spending at any time.
Another example of the circular funding in AI comes from the fact that ~44% of Anthropic’s revenue in the first nine months of 2026 came through Google and Amazon’s cloud platforms. Both are also major investors in Anthropic. At the same time, they’re also building out competing AI models and services. This situation reminds us of Beyond Meat (BYND) and that company’s failed attempt to garner shelf space in the grocery stores that were selling their own fake meat. When push came to shove, Beyond Meat did not get the shelf space.
We think the same relationship exists between hyperscalers and pure-play AI model providers. The hyperscalers are happy to help as long as it makes them money. But, if the hyperscalers ever see the pure-play AI model companies as competitors, they won’t give them any compute (i.e. shelf space) either. As we’ve said before, they can’t all be winners, but each AI stock is priced as if it will be.
Red Flag #7: No Sustainable Competitive Advantages or Pricing Power
We first wrote about the lack of competitive advantages in Anthropic and OpenAI’s business models in The Price Is Not Right For Anthropic and OpenAI. This warning is worth reiterating.
In our previous report, we found that Claude Fable 5 and Mythos 5 cost ~18x more than DeepSeek R1 for input tokens and 23x more for output tokens.
If Anthropic’s models were clearly better, they could defend that price gap. In reality, benchmark testing proves the lower cost models deliver equal or better performance, at a fraction of the cost. In other words, super low-cost Chinese models are outpacing American counterparts on both quality and pricing.
Unfortunately for potential investors, this lack of competitive advantage exists even as Anthropic is the least profitable company amongst its peers and competitors.
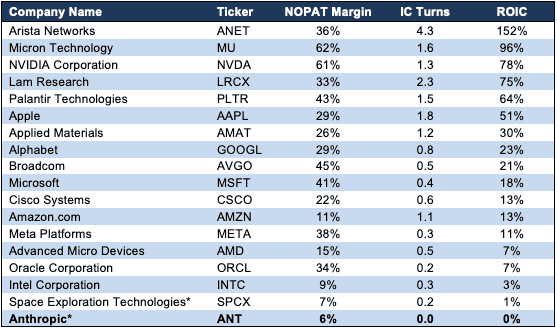
Per Figure 3, Anthropic has the lowest return on invested capital (ROIC) among tech peers, both chip makers and hyperscalers.
Without increasing prices to drive revenue higher (which makes competitors offerings more attractive), or cutting massive compute expenses (which may be unfeasible due to non-cancellable nature of agreements), Anthropic faces an uphill battle to improve its already negative profitability.
Figure 3: Anthropic’s Profitability Vs. Competition: TTM
Sources: New Constructs, LLC and company filings
*Anthropic and SpaceX NOPAT Margin, IC Turns, and ROIC represent nine months ended 2026 data, as we don’t have enough historical data to build a TTM model.
Red Flag #8: We Don’t Know if We Can Trust the Financials, Yet
As a private company, Anthropic is not required to comply with the SEC rules that implement Section 404 of the Sarbanes-Oxley Act and is therefore not required to make a formal assessment of the effectiveness of its internal control over financial reporting.
The company will be required to provide a report on the effectiveness of internal controls beginning with its second annual report following its IPO.
The company’s auditor, Ernst & Young, and Grant Thorton prior to October 2025, are required to obtain an understanding of internal controls, but not for the purpose of expressing an opinion on the effectiveness of the company’s internal controls. As a result, the auditor(s) issue no such opinion. Without an auditor’s opinion on the effectiveness of internal controls, investors are left in the dark until there is one.
Should a weakness in internal controls arise, the risk that the company’s financials are fraudulent and/or misleading increases. As the S-1 notes “Any failure to develop or maintain effective controls, or any difficulties encountered in their implementation or improvement, may adversely affect our results of operations or cause us to fail to meet our reporting obligations and may result in a restatement of our financial statements for prior periods.”
As long as they warn the public that they might be cooking the books, they cannot be held liable for fraud.
Red Flag #9: IPO Investors Get Almost No Real Voting Power
Anthropic is going public with a multi-class share structure that keeps founders and an independent trust in control regardless of how much Class A stock the public buys. As a public company, Anthropic will have five classes of common stock:
- Class F common stock, held by Anthropic Founders, LLC, which is made up of the seven co-founders, Dario Amodei, Daniela Amodei, Tom Brown, Jack Clark, Jared Kaplan, Sam McCandlish, and Christopher Olah. This Class F share holds 50.1% of the total voting power of outstanding shares.
- Class T shares, held in a separate Long-Term Benefit Trust, which is made up of “five disinterested voting trustees” who will have authority to appoint and remove four of the seven members of Anthropic’s board.
- Class E shares, given to employees, have voting rights over the election/removal of the Class T director.
- Class N shares, which are owned by Amazon and Google, hold economic rights but no voting rights. Should Amazon and Google sell these shares, they convert to Class A voting stock.
- Class A shares, which are the shares investors will buy in the IPO. These shares receive one vote per share but will always have less voting power than the founders, due to the Class F shares.
Anthropic’s S-1 lays out the voting structure clearly: “the LTBT and the Founder LLC will collectively have the ability to elect all members of our board of directors, and the Founder LLC will have the ability to determine the outcome of all matters submitted to a vote of our stockholders generally for the foreseeable future.”
Because of its governance structure, Anthropic disclosed in its S-1 that it will be a “controlled company” under Nasdaq Global Select Market governance requirements. As a controlled company, Anthropic is not required to have a majority of its board of directors composed of independent directors or establish independent compensation and nominating committees. Lack of independence at the Board level is a big red flag for us.
Do investors really want to give Anthropic a $2 trillion valuation and give a management team that regularly threatens that its business could present “existential risks” carte blanche over all decision making?
Red Flag #10: The IPO is Exit Liquidity, Not Growth Capital
Historically, IPOs serve to raise public capital to fund expansion and grow a business beyond what was possible with private capital. In return for their capital, public market investors partake in the value the capital creates.
Anthropic breaks that trend. Private markets have already funded Anthropic with $122 billion or over 50x what five of the most successful public companies in the world today raised before they went public. See Figure 4. Anthropic has raised 5x what Uber raised, which was one of the most heavily privately funded businesses in history before its IPO in 2019.
Figure 4: Anthropic Pre-IPO Capital Raises Dwarf Tech Peers
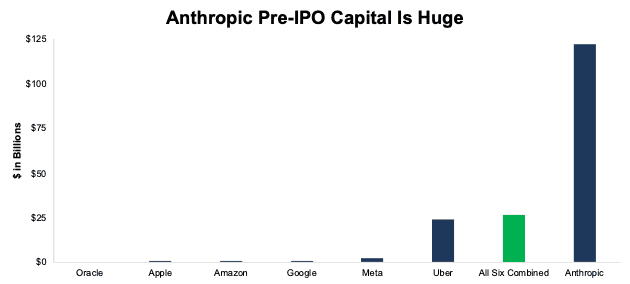
Sources: Tech Crunch, Fortune, Yahoo Finance, Bloomberg, Fundable
The bottom line is that private investors and Wall Street insiders have already loaded up on equity in Anthropic. They’ve been investors for years at valuations as low as $623 million. The most recent (May 2026) private funding valued the company at $965 billion and made Anthropic the most valuable private company ever.
It has maxed out private investors, who now need the company to tap public markets to get them their pay day.
According to The New York Times, the Anthropic IPO is set to create at least 7 co-founder billionaires and dozens of additional multi-millionaires and billionaire-tier early employees. You might say there’s a lot of Wall Street money riding on this IPO.
Red Flag #11: This IPO Is a Cashout for Insiders from Day Two
Typically, company insiders and pre-IPO investors must wait 180 days before they can sell the new publicly-traded shares, but, as noted above, Anthropic insiders can sell after day 1. Their S-1 goes on to list 23 lock-up dates at which non-founder directors, officers, and current and former employees can sell shares.
Given how much money insiders have locked up in Anthropic and how big their cash out could be, should we be surprised that they are looking to cash out?
Add in the billion plus in banker fees on the line, and we think it’s clear that the purpose of this IPO is to provide exit liquidity for insiders.
IPO Valuation Implies Ridiculous Future Revenue and Profit Growth
With the increased liabilities and decelerating revenue growth, our reverse discounted cash flow (DCF) model shows the future cash flow required to justify Anthropic’s potential $2 trillion valuation look much more ridiculous than what we showed in our last report.
To justify a $2 trillion valuation, our model shows that Anthropic would have to:
- immediately improve NOPAT margin to 12% and sustain it for the next 10 years (compared to -915% GAAP net income margin in 2025 and -313% GAAP net income margin in first nine months of 2026),
- grow revenue by 1000% in 2026 and 100% in 2027, and
- grow revenue 60% compounded annually from 2028-2035.
In this scenario, Anthropic’s:
- revenue would reach $4.3 trillion (compared to $4.6 billion in 2025), which is 1.6x the combined TTM revenue of Microsoft (MSFT), Apple (AAPL), Alphabet (GOOGL), Amazon (AMZN), NVIDIA (NVDA), Meta (META), and Oracle (ORCL).
- NOPAT would reach $520 billion in 2035, compared to the company’s -$4.5 billion NOPAT in 2025 and $2.2 billion in the first nine months of 2026. For reference, $520 billion is 2.8x NVIDIA’s $184 billion and 3.6x Microsoft’s $143 billion in TTM NOPAT.
Those expectations seem more than a bit too high for our taste.
There’s 50%+ Downside Even with Higher Margins
If we assume that:
- NOPAT margin improves to 25% over the next 10 years,
- revenue grows by 1000% in 2026 and 100% in 2027, and
- revenue grows 37% compounded annually from 2028-2035, then
Anthropic’s public equity would be worth just $1 trillion today – a 50% downside to the targeted IPO valuation.
This scenario still implies Anthropic generates $1.3 trillion in revenue and $320 billion in NOPAT in 2035. For reference, the revenue and NOPAT implied by this scenario would rank 1st across all companies we cover.
There’s 90%+ Downside Even if Anthropic is as Profitable As Meta
If we assume that:
- NOPAT margin improves to 38% over the next 10 years (equal to Meta in the TTM),
- revenue grows by 1000% in 2026 and 100% in 2027, and
- revenue grows 23% compounded annually from 2028-2035, then
Anthropic’s public equity would be worth just $152 billion today – a 92% downside to the targeted IPO valuation.
This scenario implies that Anthropic generates $507 billion in revenue and $193 billion in NOPAT in 2035. For reference, Alphabet generated $132 billion in NOPAT over the TTM and $471 billion in revenue over the TTM.
Figure 5 compares Anthropic’s implied future NOPAT in these scenarios to its historical NOPAT. We also include the 2025 NOPAT for NVIDIA for reference.
Figure 5: Anthropic’s Historical NOPAT and Implied NOPAT: DCF Valuation Scenarios
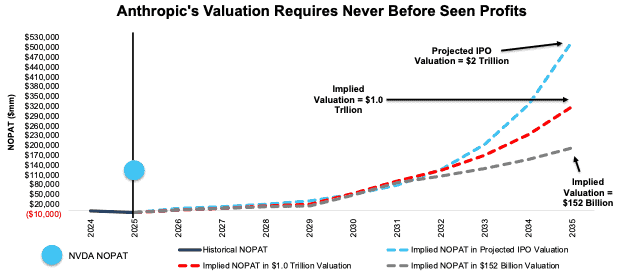
Sources: New Constructs, LLC and company filings
Each of the above scenarios assume:
- adjustments to shareholder value equal $1.3 trillion, which includes $1.0 trillion in total debt, $157.5 billion in preferred capital, and $157.7 billion in outstanding employee stock options as of September 30, 2026.
- the change in invested capital equals 50% of the change in revenue in years 1-4, and 15% of the change in revenue in years 5-10.
- Weighted average cost of capital (WACC) is 8.6%. We note that one could make a case for Anthropic to have a much higher WACC given the risky nature of its business and future obligations.
These assumptions allow us to create scenarios that demonstrate the extremely high level of expectations embedded in the projected IPO valuation. The assumptions may prove too optimistic, as the change in invested capital may be larger as the company must continually secure more compute. In that case, the profit growth required to justify the IPO price would be even higher.
This article was originally published on November 5, 2026.
Disclosure: David Trainer and Kyle Guske II receive no compensation to write about any specific stock, style, or theme.
Questions on this report or others? Join our online community and connect with us directly.