I am optimistic about the U.S. economy and I don’t believe we are in bubble. Too many investors and economists are looking at the economy the wrong way.
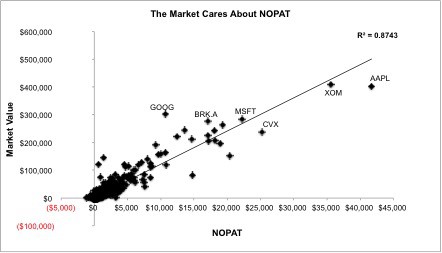
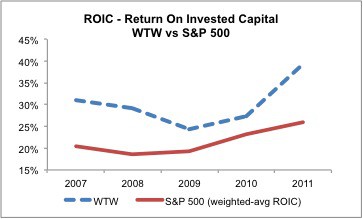
This article provides some empirical evidence behind my putting Apple (AAPL) in the Danger Zone last week because its return on invested capital (ROIC) is outrageously high. That fact underscores why valuing this company or any other with the expectation that such a high ROIC was sustainable would be a mistake.
I believe the US economy is undergoing a restructuring where we, as a society, are becoming radically more productive. I think that we are entering a new economic paradigm of productivity in both our corporate and labor markets. In this new paradigm, we achieve enough gains in productivity to offset the inflationary forces of QE.
If you bought Cisco Systems Inc (CSCO) last August when I recommended it to investors, or when I recommended it again in January, or any time between May 10, 2012 and now when the stock has had my Very Attractive rating, then today has been a good day for you.
Too many investors are looking at AAPL through the rear view mirror and assume that its sky-high profits and return on invested capital (ROIC) are sustainable. As I detail in my CNBC interview, Apple is not cheap and investors should not underestimate the impact of losing Steve Jobs.
Investors should pay little mind to recent short-term trends such as falling EPS, estimates and stock price and focus on the strong long-term fundamentals of this business.
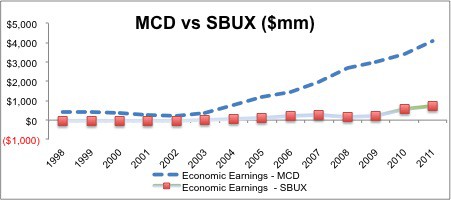
When McDonalds (MCD) made my Most Attractive Stocks list this month, I must admit I let out a small cheer. This company is one of the better-run businesses in the world. I have long eyed the stock in hopes that it would get cheap enough to dig into and now it has.
Most of my research and publishing tends to focus on companies manipulating accounting rules to make their reported earnings look better than the real economic cash flows of their business.
It is unfortunately rare that I find a company whose economic earnings are outpacing the reported accounting results and whose stock is cheap.
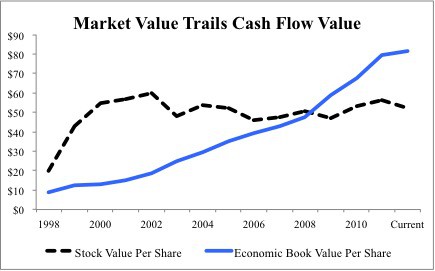
One such company is Lam Research (LRCX – very attractive rating). One of September’s most attractive stocks, LRCX offers investors hidden value.
It is only a matter of time before oil and gas stocks stop moving with the price of oil and start reflecting their underlying economics.
When this happens, Baker Hughes (BHI – “very dangerous” rating) will be among the stocks that fall the hardest.
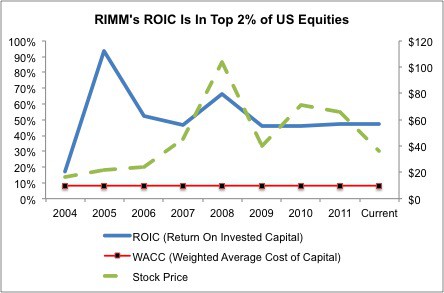
Yes, RIMM is losing market share and fast. Yes, RIMM’s Blackberry Playbook tablet is a dud. Yes, the stock has been a stinker recently. And yes, none of what I wrote at the beginning of this article would matter if the stock were not super cheap.
Recent weakness in Intel (INTC)'s stock presents an excellent buying opportunity for investors. As one of March’s most attractive, INTC offers the rare combination of strong cash flow growth with a remarkably cheap valuation.
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that DFS’s current valuation (stock price of $21.80) implies that the company’s profits will decline by 40% and never grow again.
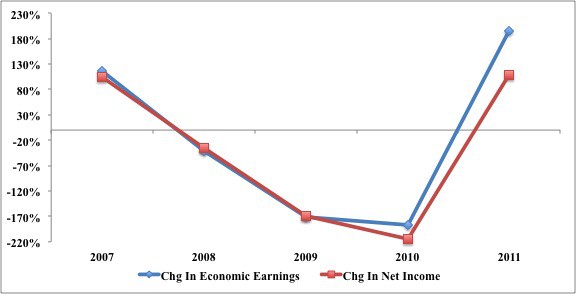
2. Economic earnings are growing faster that reported accounting earnings.
3. Free cash flow of $2.8bn or 24% of its enterprise value during the last fiscal year.