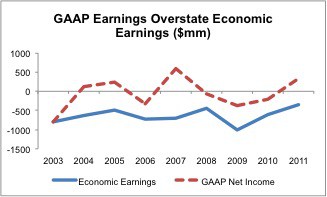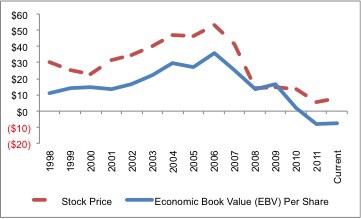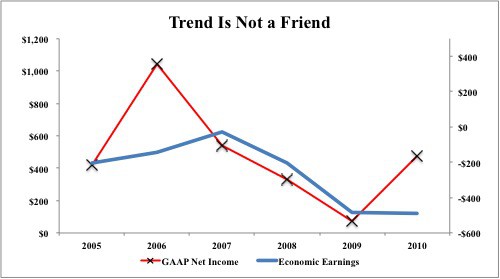
Goodyear Tire & Rubber (GT) must overcome $3.7 billion in underfunded pensions plus $6.3 billion in debt ($1.1 billion of which is off balance sheet) before investors could see any upside.
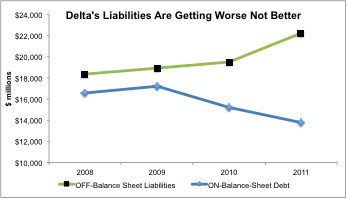
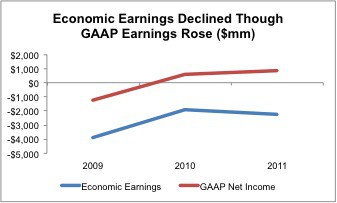
I recommend investors avoid Delta Airlines (DAL). I think the stock could see significant downward pressure as more investors realize how the company is propping up its earnings with relatively aggressive accounting for its pension and postretirement plan (“pensions”), which are already seriously underfunded.
Be wary of advice from the bandwagon riders. They care more about getting more people in the bandwagon than anything else.
The Starbucks (SBUX) bandwagon is a big one. I am not on it.
Year to date, Bank Of America (BAC) stock is up nearly 45% compared to the S&P at +about 8%. BAC stock has bounced back nicely after dropping precipitously at the end of last year.
I would call the 45% bounce a “dead cat” bounce because I expect the stock to fall right back to $5/share, where it bottomed last Thanksgiving, or lower.
Recent news that Bank Of America (BAC) is considering jacking up its fees on basic checking accounts suggests the company is bad shape. As I wrote yesterday, I believe BAC stock is headed back to its lows and today’s news confirms my view that the expectations basked into the stock’s valuation are writing checks that the company cannot cash.
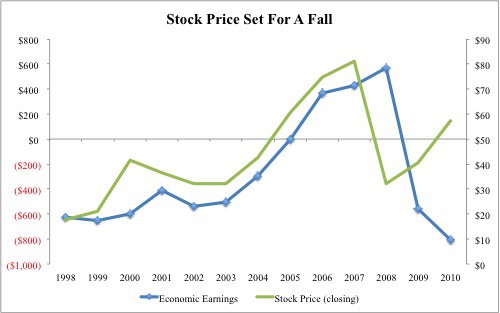
Do not be fooled by the recent stock market run-up. Think of it as a set-up for a fall. Investors need to protect their portfolios from the eventual economic decline that will stem from the euro debacle.
Here is the explanation behind why I suggested investors "brace" their portfolio and go net short in my "Don’t be fooled: Get short now" column on MarketWatch.com. In addition, I provide free reports on the stocks and funds I suggest shorting.
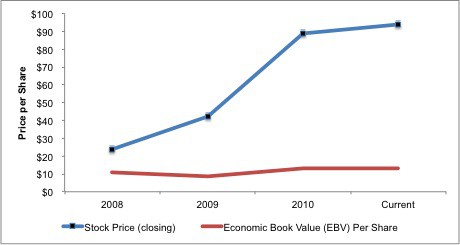
VMW’s valuation has its head in the clouds.
This stock is a great short in most any scenario and is especially attractive in the event of a global economic slowdown led by a recession in Europe.
High dividend yields are NOT enough to warrant investing in the utilities sector.
Too many investors put their hard-earned money in utility stocks with the assumption that relatively high-yielding dividends from stable business make a good investment.
The real question that investors in any equity security must ask is: does my expected return from a stock justify the risk of investing in it?
Similar to my prior interviews on SBUX, I found it easy to make the bear case for a stock that is as expensive as Starbucks (SBUX). As my regular readers know, when I say "expensive", I back that up with details such as: to justify its $40 stock price (closing price from prior day), SBUX had to grow profits at 10% compounded annually for more than 25 years.
In addition to my stock-brawl interview on Thursday (9/29/11), I have commented to the media on Starbucks (SBUX) many times. Below is a list (with links) to my past opinions/comments on SBUX.
It is only a matter of time before oil and gas stocks stop moving with the price of oil and start reflecting their underlying economics.
When this happens, Baker Hughes (BHI – “very dangerous” rating) will be among the stocks that fall the hardest.
Accounting rules provide the biggest loopholes to asset intensive businesses. And the off-balance sheet operating lease loophole is one of the biggest.
By exploiting this loophole, Starwood is able to omit nearly $1 billion in debt from its balance sheet in 2010, $200 million (20% of the total) was added in 2010.