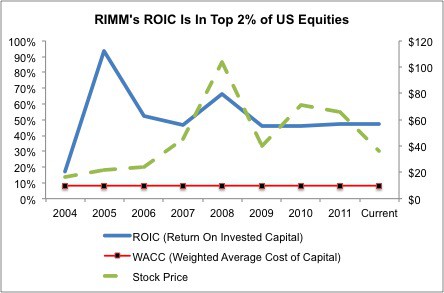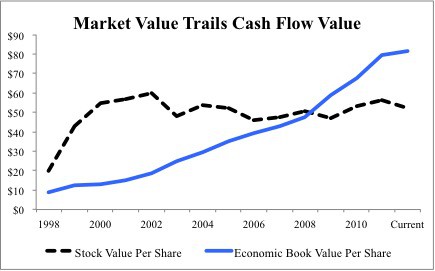
Yes, RIMM is losing market share and fast. Yes, RIMM’s Blackberry Playbook tablet is a dud. Yes, the stock has been a stinker recently. And yes, none of what I wrote at the beginning of this article would matter if the stock were not super cheap.
I am not a smoker or tobacco user, and I do not like to be around smokers. However, that prejudice does not blind me from the fact that Lorillard, Inc. (LO) is a “very attractive” stock. I recommend investors buy it as well as the following ETFs because of their large allocations to LO and their attractive-or-better investment ratings...
The risk/reward of this stock is quite compelling. Downside risk is low as the valuation already implies a permanent 54% decline in profits. How much worse can the valuation get? Upside reward potential is strong as the stock has to go over $77/share to trade at a value that implies the company’s profits will experience a 0% decline, still a no-growth scenario.
Since we made DFS the Stock Pick of the Week on Feb 15, 2011, the stock is up about 14% while the S&P500 is up about 0.3%. The stock was super-cheap when we made the call, and that is no longer the case. After making the February and March lists, DFS is no longer one of our Most Attractive Stocks in April.
Recent weakness in Intel (INTC)'s stock presents an excellent buying opportunity for investors. As one of March’s most attractive, INTC offers the rare combination of strong cash flow growth with a remarkably cheap valuation.
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that DFS’s current valuation (stock price of $21.80) implies that the company’s profits will decline by 40% and never grow again.
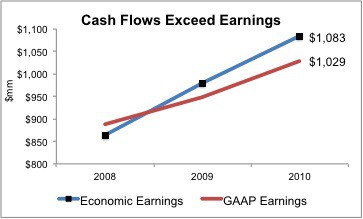
2. Economic earnings are growing faster that reported accounting earnings.
3. Free cash flow of $2.8bn or 24% of its enterprise value during the last fiscal year.
HIDDEN GEM: ABT's current stock price (~$45 per share) implies the company’s profits will permanently decline by 20%. In other words, the market is not only giving no credit for future profit growth, it is predicting a significant (20%) decline in profits.
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that KIRK’s current valuation (stock price of $13.25) implies that the company’s profits will decline by 50% and never grow again.
2. Economic earnings are growing faster that reported accounting earnings.
3. Free cash flow of $32.2mm or 12.4% of its enterprise value during the last fiscal year.
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that APOL’s current valuation (stock price of $42.31) implies that the company’s profits will decline by 60% and never grow again.
2. Economic earnings are higher than reported accounting earnings.
3. Excess cash of $1,201mm or about 20% of its market cap
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that ACN’s current valuation (stock price of $48.59) implies that the company’s profits will decline by 9% and never grow again.
2. Economic earnings are higher than reported accounting earnings.
3. Excess cash of $3,728mm or about 12% of its market cap
HIDDEN GEMS:
1. About $15 million in non-operating expenses (after-tax) cause reported earnings to be understated.
2. Our discounted cash flow analysis shows that ADI’s current valuation (stock price of $37.18) implies that the company’s profits will decline by 10% and never grow again.
3. The company grew its economic earnings by $283mm during its last fiscal year.
4. Excess cash of $2,462.5mm or nearly 25% of its market cap
HIDDEN GEMS:
1. About $29 million in non-operating expenses (after-tax) cause reported earnings to be understated.
2. Our dis¬counted cash flow analy¬sis shows that TRV’s cur¬rent val¬u¬a¬tion (stock price of $55.49) implies that the company’s profits will decline by 30% and never grow again.
3. The company grew its economic earn¬ings by $827mm during its last fiscal year.
HIDDEN GEM: Our detailed valuation model shows that WDC grew its “economic” profits by 226% while accounting profits grew 194% during its last fiscal year. Economic profits rose by $769mm while accounting profits rose by $912mm.
HIDDEN GEMS:
1. About $250 million in non-operating expenses (after-tax) cause reported earnings to be understated during the last fiscal year.
2. Our discounted cash flow analysis shows that CL’s current valuation (stock price of $77.52) implies that the company’s profits will decline by 7% and never grow again.
3. The company grew its economic earnings by $229mm (14% increase) during its last fiscal year.
MSFT released better than expected earnings and is up 8.3% since it was named the Stock Pick of the Week on October 28, 2010. Overt the same time period, the S&P 500 is up only 3.6%.
HIDDEN GEMS:
1. Our discounted cash flow analysis shows that BMY’s current valuation (stock price of $27.16) implies that the company’s profits will decline by 35% and never grow again.
2. The company grew its economic earnings by $307.5mm (12% increase) during its last fiscal year.
3. The company has $9,507mm in Excess Cash, which we remove from our Invested Capital calculation. $9,507mm million is more than 20% of BMY’s market cap.
HIDDEN GEM: AAPL's economic earnings rose more than its accounting earnings during the last fiscal year. Economic earnings rose by $3,576 while accounting earnings rose by $2,401. And the company has $31,849mm in Excess Cash, a reflection of the strong profitability of the business.